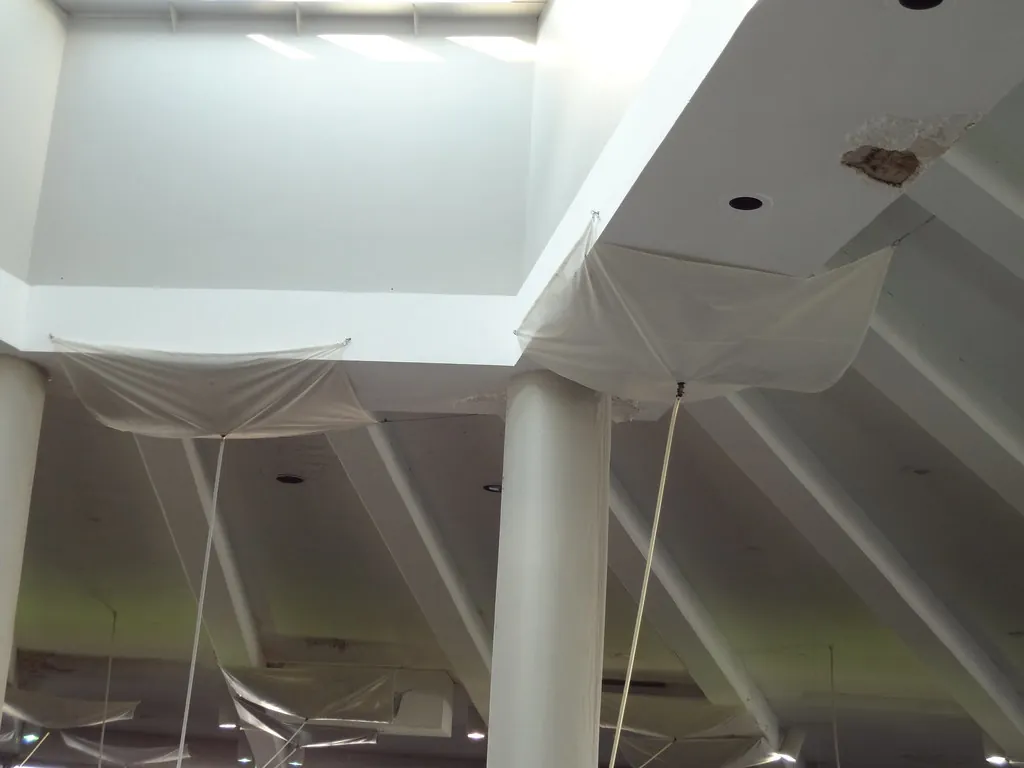
Water losses grow out of sight
A failed supply line behind a refrigerator or a leaking water heater in a Johnson County basement can wet subfloor, base trim, lower drywall and insulation in several rooms before anyone notices. The visible stain is usually the smallest part of the loss.
Where estimates come up short
- Flooring replaced in one room when the same continuous floor runs through the whole level.
- Cabinets “detached and reset” when water-damaged particleboard bases can’t be reused.
- Drying charges without the equipment logs and moisture readings to support them.
- Paint limited to patched walls instead of corner to corner for a uniform finish.
- Contents in basement storage left off entirely.
Coverage lines to understand first
Water claims sit close to coverage boundaries. Flood (surface water) is generally excluded from homeowner policies and covered separately through flood insurance. Sewer and drain backup usually needs an endorsement with its own limit. Repeated seepage over weeks may be excluded. Appraisal can’t resolve those questions, but where coverage is accepted, it can resolve the size of the loss.
What we bring
We trace the water path, record readings, review drying logs and build a complete repair scope. If the dispute is about matching, we document the continuous flooring and finishes so the panel can see why a partial repair won’t restore the home.
Frequently asked questions
Is flooding from heavy rain covered?
Usually not under a standard homeowner policy. Surface water flooding typically requires a separate flood policy. Water from a burst pipe is different.
My policy has a water backup endorsement. Does appraisal apply?
If the loss falls under that endorsement and the dispute is the amount, appraisal can apply, subject to the endorsement’s limit.
Can you help with mold?
We value mold remediation as part of the repair scope where it’s covered. Many policies cap mold coverage, so check your limits.