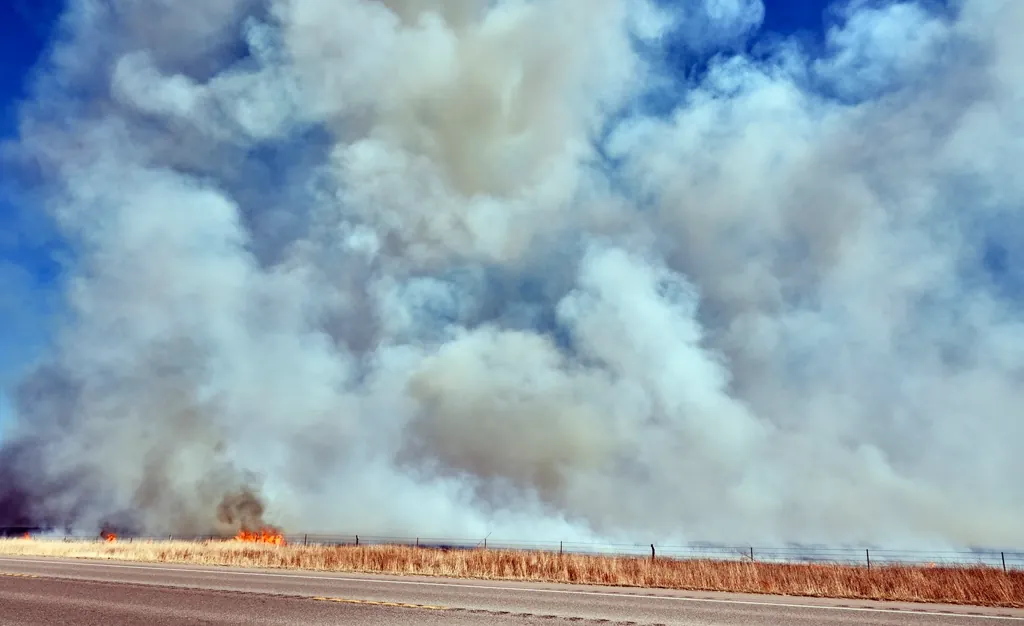
Fire on the prairie
Grassland fire is part of Kansas life. Ranchers burn the Flint Hills on purpose each spring, but wind-driven wildfires are something else. The 2016 Anderson Creek fire and the 2017 Starbuck fire burned hundreds of thousands of acres in south-central and southwest Kansas, and the December 15, 2021 windstorm drove the Four County Fire across Russell, Ellis, Osborne and Rooks counties. Fires like these destroy homes, barns, fencing and livestock facilities in a matter of hours.
What makes rural fire claims hard
- Fencing. Miles of barbed wire, pipe and panel fence are priced per linear foot, but terrain, post type and access all change the real cost.
- Outbuildings. Pole barns, machine sheds and grain bins may fall under different coverages or schedules.
- Smoke damage. Homes that didn’t burn may still need cleaning, filter changes, duct cleaning or more.
- Debris removal. Clearing burned structures and hazardous materials on rural sites is expensive and slow.
- Contractor scarcity. After a regional fire, crews are booked for months and prices rise.
How we help
We value homes, outbuildings, fence and smoke damage line by line, using pricing that reflects rural access and post-fire demand. If you farm or ranch, we also help organize what falls under a farm policy versus a homeowner policy, so each item is valued under the right coverage.
Frequently asked questions
Is fence covered after a grass fire?
It depends on the policy. Some farm policies cover fence as scheduled farm property; many homeowner policies limit it under Other Structures.
Can appraisal handle smoke damage to a house that didn’t burn?
Yes. If the insurer accepts smoke damage and the dispute is the cost to clean or replace, appraisal can set that amount.
Do you travel to western Kansas?
Yes. We work statewide, including Clark, Comanche, Barber, Ellis, Russell and other rural counties.