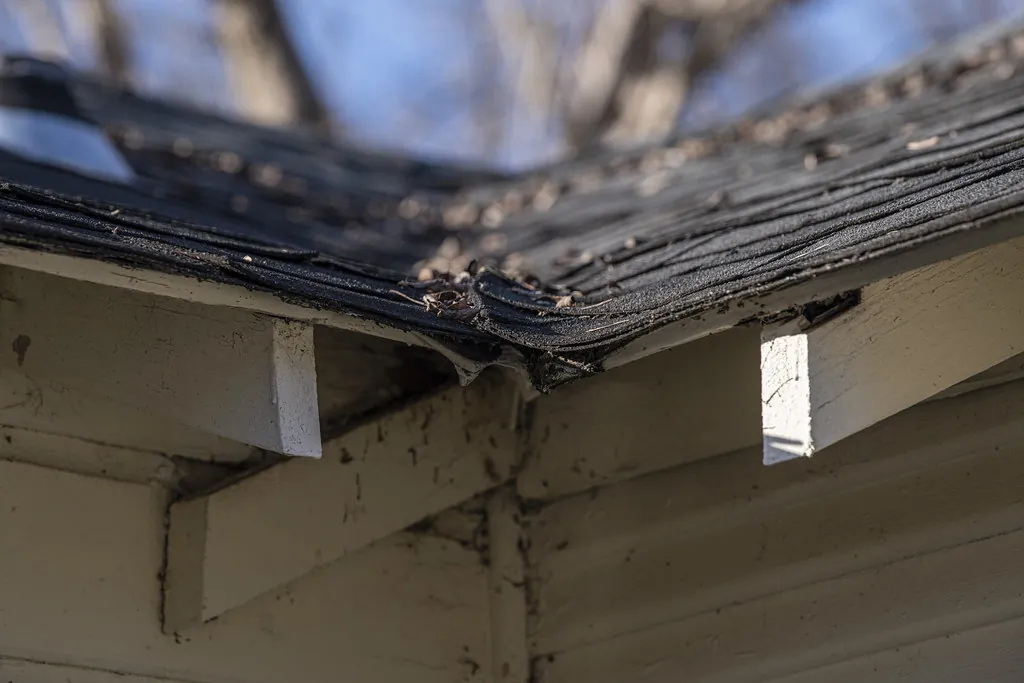
Hail is the Kansas claim
Kansas regularly ranks among the states with the most hail claims. Insurers have responded with three policy features that change how much a hail claim pays: roof payment schedules, cosmetic damage exclusions and percentage wind/hail deductibles. None of them changes how much damage the storm did. All of them change the check.
1. Roof payment schedules
A roof schedule pays a set percentage of roof replacement cost based on age. A five-year-old roof may be paid at most or all of its replacement cost; a fifteen-year-old roof may be paid at well under half. Unlike ordinary depreciation, the reduction usually isn’t recoverable after repairs.
Two practical points: confirm the roof age the insurer used, and make sure the replacement cost the schedule is applied to is complete. A higher, accurate roof valuation still raises the scheduled payment. Try the roof age payment schedule calculator to see the effect.
2. Cosmetic damage exclusions
Often attached to metal roofing, these exclusions remove coverage for dents that don’t affect function, meaning the roof still sheds water. Whether specific damage is cosmetic or functional can be contested, and that question often turns on coverage rather than cost.
3. Percentage wind/hail deductibles
A 1% or 2% deductible on a $300,000 dwelling limit is $3,000 or $6,000. On a modest hail claim, that can absorb most of the payment. Use the percentage deductible converter to see yours in dollars.
Where appraisal fits
Appraisal sets the amount of loss: the full replacement cost of the damaged roof, siding, gutters and other items. The policy’s schedule, exclusions and deductible are then applied to that number. If the insurer under-measured the roof or approved only some slopes, appraisal can correct the base number even when a schedule applies.