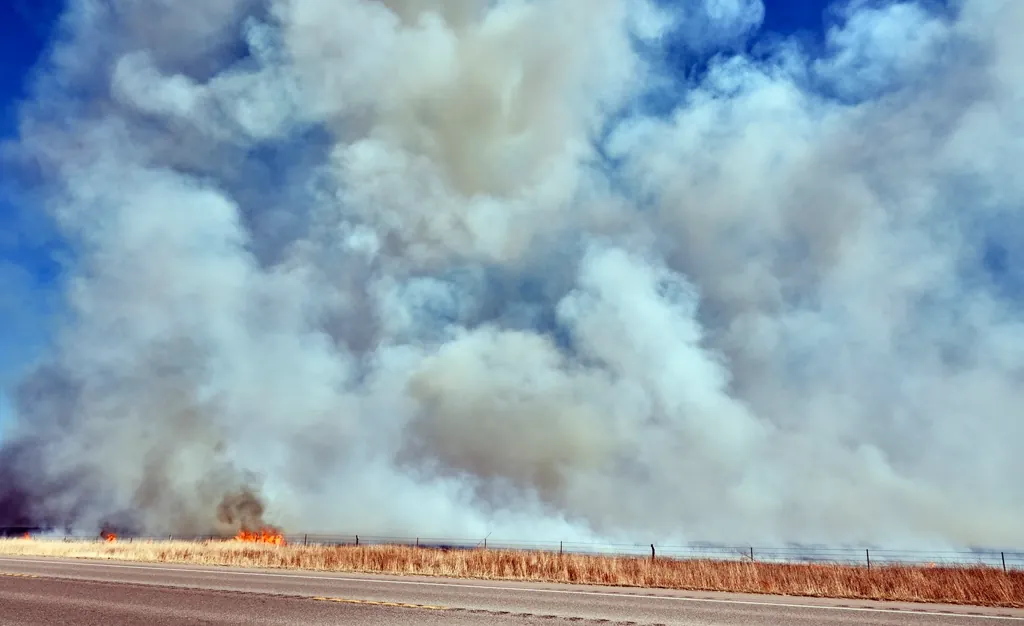
Fast fires, wide losses
When dry grass meets strong wind, Kansas fires can travel for miles. The 2016 Anderson Creek fire, the 2017 Starbuck fire and the 2021 Four County Fire each burned homes, barns, fence and pasture over huge areas. Claims after fires like these involve many kinds of property at once.
Sort your coverages first
Farm and ranch policies often schedule buildings, fence and equipment separately with their own limits and valuation. A homeowner policy may cover fence only under Other Structures. Start by matching each damaged item to the coverage that applies.
Fence
Fence is priced per linear foot, but the real cost depends on post type, wire, terrain, access and how much old fence must be removed. Document lengths, types and conditions with photos and maps.
Outbuildings and equipment
Pole barns, sheds and bins may be insured at actual cash value. Equipment may need specialist valuation. Keep purchase records and photos.
Smoke damage
Homes that didn’t burn can still have smoke and soot in HVAC systems, attics and contents. Cleaning protocols and replacement decisions are a frequent source of disagreement.
Where appraisal helps
When coverage is accepted and the dispute is cost, appraisal can resolve fence, building and smoke-cleaning values with documentation that reflects rural realities.